

 한국어
 English
 日本語
 Tiếng Việt
 简体中文
베트남의 가내 사업자들은 비공식 도매 채널에서 벗어나 공식 채널과 검증된 공급처로 이동하고 있습니다.
183월2026
최신 뉴스 및 보고서 / 베트남 브리핑
댓글: 댓글 없음.
추상적인
Vietnam’s informal economy has long shaped how small businesses source their goods. For decades, household business operators have relied on traditional wholesale markets, places like Đồng Xuân in Hanoi and Bình Tây in Ho Chi Minh City, to procure inventory quickly, cheaply, and without paperwork. However, this model is changing fast. A convergence of regulatory pressure, digital infrastructure, and shifting business incentives is driving a structural transition in how Vietnamese small and micro-businesses purchase goods. Increasingly, Household business operators are moving away from informal wholesale channels toward formal-channel sourcing: licensed distributors, B2B e-commerce platforms, and verified suppliers who can issue VAT invoices.
Understanding the Starting Point: The Dominance of Informal Sourcing
Vietnam’s retail sector is characterized by a high density of household business – small, often family-run businesses that operate under a simplified tax registration rather than as formal enterprises. According to the National Statistics Office, as of the end of July 2025, Vietnam had approximately 6 million household businesses, of which more than 1.9 million were registered. In the first seven months of 2025 alone, nearly 536,200 new household businesses were established, representing an increase of almost 165% compared to the same period in 2024[1].
These businesses have historically procured goods through wholesale markets, informal traders, and direct manufacturer contacts – channels defined by cash transactions, oral agreements, and an almost total absence of documentation. The advantages of this approach were clear: lower prices (partly due to tax avoidance), faster transactions, flexible credit arrangements, and proximity. Wholesale market vendors understood the needs of small buyers. There was no minimum order requirement, no formal registration, and no invoice necessary.
However, the limitations of informal sourcing have become increasingly evident. Without VAT invoices, household businesses cannot claim input tax deductions, raising their effective costs. The lack of formal procurement records also restricts access to bank financing, while undocumented supply chains increase exposure to quality and regulatory risks. As Vietnam’s regulatory environment matures and digitizes, these constraints are becoming more significant.
Shifting Buyer Sourcing Behavior
Recently, due to tighter regulations and greater awareness, more firms are moving to official channels (authorized dealers, B2B e-commerce, and approved importers) that issue VAT invoices. For example, a 2025 Sapo Technologies survey of 15,000 retail and F&B sellers found that compliance with tax regulations and electronic invoicing are becoming essential. 57.3% of retailers said they had basic knowledge of tax/invoice rules, while 42.7% struggled and cited difficulty issuing e-invoices, signaling a learning curve. Importantly, demand for e-invoicing is broad: nearly half of respondents issue > 10,000 invoices/year (large buyers) and another 45% issue 1,000 – 10,000/year[2]. This trend toward standardization implies that many businesses are scaling up operations and seeking official invoicing. For Vietnamese sellers, growth is no longer the sole objective, but is increasingly accompanied by the need for structured operations, tax compliance, and risk control.
Small traders are being guided on sales management, invoicing, and tax filing
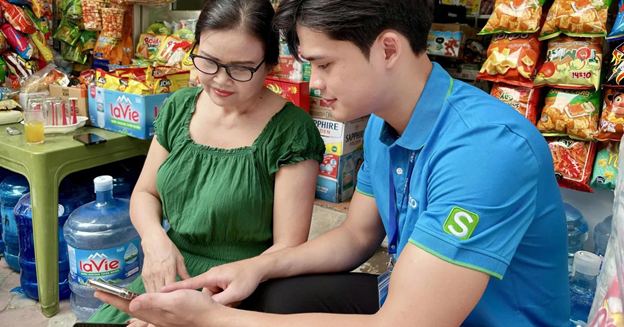
출처: 바오 투오이 트레
The Drivers of Change: Why Household Businesses Are Moving Toward Official Channels
Tax Policy and the Incentive to Formalize
Vietnam has tightened VAT and invoicing rules. E-invoicing is mandatory nationwide under Decree 123/2020[3], and the revenue threshold for VAT registration for small businesses has been raised from VND 200 million to VND 500 million, effective from 2026[4], reducing regulatory pressure on smaller businesses.
Recent tax reforms even allow some purchases (e.g., farm produce, handicrafts) without invoices to be recorded via purchase lists, highlighting that most other B2B spending does require formal VAT invoices. New VAT-law amendments (effective 2025-26) reduce dependence on seller declarations for input-tax claims, further encouraging buyers to secure valid VAT invoices themselves. In practice, buyers now risk losing tax deductions (or incurring penalties) if they purchase from sources without proper invoices. Enforcement is also intensifying: counterfeit goods crackdowns and business audits push firms away from opaque supply channels.
The Rise of B2B E-Commerce Platforms
The growth of digital platforms and e-procurement makes official sourcing easier. Mobile ordering, digital catalogs, and e-payment are spreading even among SMEs. B2B marketplaces and digital distributors offer catalogues, automated invoicing, and delivery services. Platforms such as OneShop, MM Pro, and international marketplaces (Amazon, Alibaba,…) provide integrated solutions that combine product discovery, ordering, logistics, and automated VAT invoicing.
This removes friction: a buyer can quickly compare official suppliers online, place orders with electronic payments, and receive an e-invoice automatically. Digital VAT-invoicing systems (with real-time reporting to tax authorities) have been rolled out nationwide, making formal invoicing a norm. In summary, technology is lowering the barrier to buying “official-sourced goods” and raising the cost of staying informal.
Bank Credit and Supply Chain Transparency
Vietnam’s banking sector has grown significantly more sophisticated in its approach to SME and micro-business lending. Increasingly, loan products for working capital and inventory finance require documentary evidence of procurement – purchase orders, invoices, and delivery records. A household business operator that sources through formal channels and accumulates a documented procurement history is, in the eyes of a bank, a meaningfully more creditworthy borrower. Global trends, such as traceability in F&B and supply security in technology, are increasingly influencing Vietnam. Businesses are placing greater emphasis on certified inputs, and official channels naturally provide documentation of product origin. Marketplaces and distributors often highlight certified or branded goods, while informal markets lack this capability.
Implications for B2B suppliers
Pricing and Margins
Selling with VAT invoices allows buyers to reclaim input tax, effectively reducing the net purchase cost by around 10% when fully deducted. Suppliers therefore need to reconsider whether to list VAT separately or incorporate it into pricing and margins. Many choose to present VAT-inclusive prices to remain competitive, while some may compress margins to match grey-market alternatives, relying on higher volume. Others differentiate by bundling services such as logistics or after-sales support to justify slightly higher prices. In all cases, suppliers should recalibrate their cost structures based on the assumption that buyers factor in VAT recovery.
Invoicing and Accounting
Suppliers need to invest in compliant invoicing systems, such as e-invoicing software and digital signatures, to meet regulatory requirements. The law mandates the timely issuance of e-invoices and real-time reporting, which increases administrative costs related to IT systems and staff training. However, these investments also help formalize bookkeeping and improve operational transparency. In addition, prompt invoicing can accelerate cash flow, as buyers are more likely to pay upon receiving digital invoices. Suppliers should therefore establish efficient invoicing processes to avoid delays, especially as many businesses still face challenges in issuing e-invoices, as noted in the Vietnam News survey.
Logistics and Delivery
Formal channels often demand higher service levels. Distributors and platforms expect reliable deliveries, standardized packaging, and sometimes smaller mixed loads (e.g. “ready-to-ship” kits on Alibaba). Suppliers transitioning to officially-sourced goods may need to upgrade warehousing and transport (possibly partnering with third-party logistics). They also have to handle returns and warranties formally, as official channels typically include after-sales service agreements.
Payment Terms
Formal invoicing means payment by traceable methods. Many official buyers now insist on bank transfers (required for transactions ≥VND5 million by law for deductible VAT). Suppliers may need to shift from cash-based sales to bank/payment gateways. This can lengthen payment cycles (e.g., 30–60 days credit) but also lowers cash handling risk and may allow financing (e.g., invoice discounting).
Recommendations for foreign enterprises
For foreign companies entering Vietnam, a data-driven understanding of local sourcing behavior is critical. B2B buyer-behavior research can help identify which segments are transitioning fastest to VAT-compliant sourcing, how price sensitivity differs across sectors, and what factors drive supplier selection in a market still partly informal.
In parallel, competitor and channel analysis is essential to understand how local distributors operate, who already offer VAT-invoiced sales, how pricing is structured, and which customer segments are underserved. This is particularly important in Vietnam, where informal and formal channels coexist, and competitive dynamics are not always transparent.
Foreign entrants should also evaluate pricing and margin implications under Vietnam’s VAT system, as well as assess local logistics and fulfillment capabilities to ensure alignment with market expectations. Finally, staying up to date with evolving tax and invoicing regulations is crucial, as compliance requirements can directly shape go-to-market strategy and partnership decisions.
더 보기
* 이 기사에서 정보를 인용하고자 하신다면 출처를 원문 기사 링크와 함께 인용하여 저작권을 존중해 주시기 바랍니다.
| B&Company
2008년부터 베트남에서 시장 조사 전문 기업으로 활동해 온 최초의 일본 기업입니다. 산업 보고서, 업계 관계자 인터뷰, 소비자 설문 조사, 비즈니스 매칭 등 폭넓은 서비스를 제공합니다. 또한, 최근에는 베트남 기업 90만 개 이상의 데이터베이스를 구축하여 파트너 발굴 및 시장 분석에 활용하고 있습니다. 문의 사항이 있으시면 언제든지 저희에게 문의해 주세요. info@b-company.jp + (84) 28 3910 3913 |
[1] https://nief.mof.gov.vn/kinh-te-xa-hoi/tinh-hinh-hoat-dong-cua-ho-kinh-doanh-o-nuoc-ta-hien-nay-11682.html
[2] https://www.sapo.vn/bao-chi-noi-ve-sapo/Sapo-Khao-sat-15-000-nha-ban-hang-Thue-hoa-don-dien-tu-da-kenh-va-AI-dinh-hinh-t-a2788.html
[3] https://thuvienphapluat.vn/van-ban/Ke-toan-Kiem-toan/Nghi-dinh-123-2020-ND-CP-quy-dinh-hoa-don-chung-tu-445980.aspx
[4] https://en.baochinhphu.vn/law-on-personal-income-tax-approved-111251210112819468.htm
관련기사








로그인 / 회원가입
뉴스레터 구독