

 简体中文
 English
 日本語
 Tiếng Việt
 한국어
河内的餐饮市场正在从传统的市中心集群模式向受多种因素影响的更加分散的模式转变。
2511 月2025
最新新闻与报告 / 越南简报
评论: 没有评论.
过去十年,越南食品与饮料市场快速扩张,并持续成为东南亚最具发展潜力的消费领域之一。在所有本地市场中,河内凭借其高密度的城市人口、不断壮大的中产阶级以及活跃的餐饮文化脱颖而出。然而,正是这些使河内具有吸引力的特质,也令其竞争尤为激烈,尤其对于容错空间有限的新进入者而言。选择合适的餐饮选址,已成为餐厅、咖啡馆、快休闲品牌或甜品连锁店必须作出的最具战略意义的决策之一。.
越南餐饮市场概览
越南餐饮服务业规模庞大且仍在持续增长。Statista估计,该行业在2025年的规模已超过247.7亿美元,预计到2027年初将达到US$36.86亿美元[1], ,对应9.7%的复合年增长率(CAGR)。截至2024年底,越南约有323,010家经营中的餐饮门店,同比增长1.8%。2024年行业总收入估计为688.8万亿越南盾(US$26.96亿美元),较2023年增长16.6%[2].
2025年上半年,一项针对约3,000家餐馆和咖啡馆的调查显示,54.0%的企业收入保持稳定或实现增长,较去年同期的40.2%呈现出更为积极的前景。然而,市场仍在经历强力出清,17.9%的企业遭遇严重下滑,另有一部分企业持续面临运营挑战[3]. 。这些数据表明,尽管整体需求正在复苏,但许多经营者仍容易受到成本上涨和竞争压力的影响。.
餐饮企业经营表现(2025年上半年)
100% = 3,000家餐馆和咖啡馆
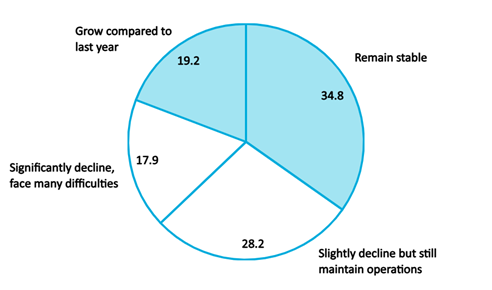
(来源: iPOS.vn和Nestlé)
此外,在2020年之前,大多数品牌都在激进扩张,瞄准任何可获得的高客流零售空间。那个时代已经结束。据越南计划与投资部数据,仅2024年前九个月,越南就有超过51,000家餐厅、咖啡馆、街头餐饮店和餐饮 kiosks 关闭[4]. 。这波关店潮反映出日益上涨的租金、通胀压力、激烈的竞争以及消费者群体日益增强的选择性。.
在主要城市,就座式餐饮仍占据消费支出的主导地位,但根据Decision Lab的《2024年在线食品配送报告》,外卖如今占餐饮交易总额的10-12%,高于2018年的仅3%。外卖的高渗透率也意味着,如果企业能够通过3-5公里配送半径获取相当一部分收入,经营者应避免为核心地段的高端位置支付过高租金。.
选址策略在河内餐饮市场中的关键作用
河内不仅是越南的政治和行政首都,也是越南消费驱动型城市之一。越南国家统计局估计,2024年河内占越南餐饮服务总支出的22%以上,尽管其人口占全国总人口的比例要小得多。超过67%的居民年龄在40岁以下,这为咖啡馆、甜品连锁店、休闲餐厅和适合外卖的餐饮业态创造了有利的人口结构。同时,家庭收入也在快速增长。具体而言,根据B&Company的数据,2020年至2024年期间,河内家庭平均月收入从1,520万越南盾增至2,280万越南盾,增幅达45%。巴亭、西湖、纸桥和青春等主要城市辖区目前报告的月收入超过2,400万至2,800万越南盾,反映出中产阶级消费者基础快速扩大,其在外出就餐和高端餐饮业态上的消费意愿也更强。.
租金压力与不断上涨的运营成本
随着城市零售市场日趋成熟,房东纷纷通过提高租金来应对需求,尤其是在客流量和品牌曝光度最强的核心商业区。CBRE Vietnam发布的《2024年零售市场展望》显示,河内最繁华辖区的优质临街商铺租金较上一年上涨了8-15%[5], ,在某些情况下,尽管宏观经济情绪疲弱,租金仍持续上涨。.
2024年,河内中心城区如还剑郡和二征夫人郡的一层平均租金达到每平方米每月172.7美元[6], 而 Vincom、Lotte、Aeon 和 Trang Tien Plaza 等高端购物中心则可以收取更高的租金。因此,仅租金一项如今就占据许多运营商总收入的20-55%,是全球基准的2-3倍[7]. 这意味着,即使存在客户需求,糟糕的选址也可能摧毁盈利能力,因为收入可能不足以抵消固定成本负担。.
Retail Occupancy and Rental Price Trends (Hanoi, 2021-Q1 2025)
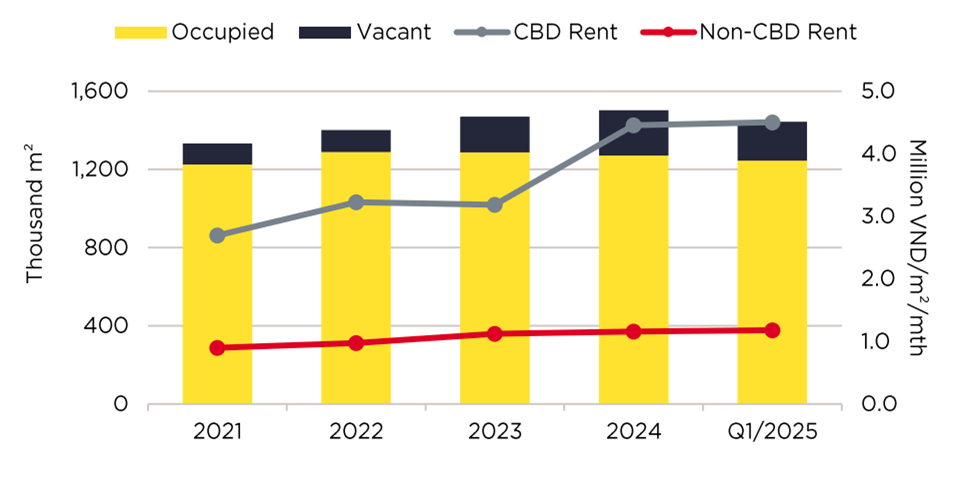
来源: Savills Vietnam
据 Savill Vietnam 称,2021年至2025年第一季度期间,中央商务区(CBD)的租金大幅上涨至近460万-470万越南盾/平方米/月,反映出市场对核心地段的激烈竞争;与此同时,随着郊区消费和配送需求不断扩大,非CBD区域的租金也持续稳步上涨[8]. 租金差距的扩大表明,未来餐饮业增长将日益转向价格更可负担的非CBD区域,那里不断上升的人口密度能够支持可持续的单店经济模型。.
此外,越南餐饮市场也已成为东南亚竞争最为激烈、饱和度最高的餐饮战场之一。Euromonitor估计,2022年至2024年期间,该市新增了数百家门店,这一趋势在 Cầu Giấy、Xuân Thủy、Times City 和老城区等主要街区尤为明显。在新店不断开设的同时,许多规模较小的独立经营者也因租金上涨、客户留存率低以及营销成本高昂而退出市场。.
配送驱动型消费正在降低对街道可见度的依赖
第二个驱动因素是线上餐饮配送的发展,这正在削弱位于繁华街道所带来的传统优势。Decision Lab《2024年线上餐饮配送报告》显示,配送收入目前约占全国餐饮消费总额的12%,而五年前仅为3%。GrabFood、ShopeeFood等餐饮配送平台加剧了市场竞争,这意味着餐厅不能再仅依靠实体客流来推动销售。因此,餐厅必须超越步行客流来思考选址。若一个地点无法支持快速取餐、高效骑手通行、高效厨房出餐,或无法覆盖理想的配送半径,即使地址热门,也不再能保证经营表现。无法有效整合配送业务的门店往往表现不佳,即使位于高端街区也是如此。.
选址作为品牌定位的组成部分
第三个驱动因素是选址所带来的品牌价值。高端概念只有在周边环境能够传达高端定位时才能取得成功。家庭休闲型餐厅在学校、办公楼或公寓聚集区附近表现最佳,因为这些区域的客流稳定且可预测。甜品和咖啡连锁品牌则高度依赖学生和年轻专业人士密集的年轻客群区域。越南消费者越来越倾向于将品牌质量与餐饮门店所在位置本身联系起来。这也是为什么位于低收入社区的高端餐厅,或反过来,在高租金购物中心内销售低毛利菜单产品的门店,往往难以实现盈亏平衡。选择错误的商圈会导致价格、品牌认知和消费能力之间出现错配。.
河内不同餐饮模式的选址策略
河内餐饮市场正从传统的市中心集聚模式,转向受郊区扩张、人口迁移和数字化消费塑造的分散化模式。随着购买力向外围扩散以及大型住宅城镇逐渐成熟,未来3-7年最具盈利能力的选址将与过去十年大不相同。.
高端餐饮与目的地型业态
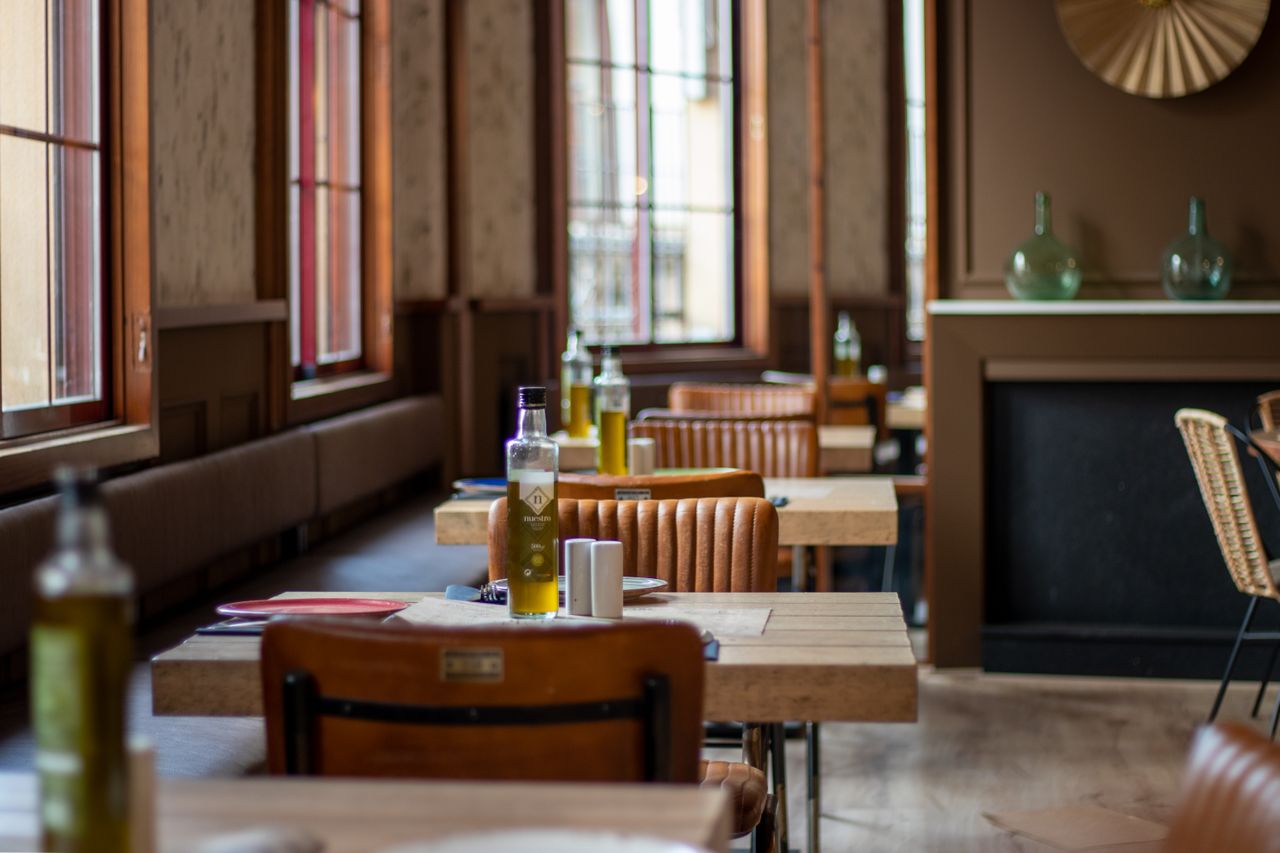
河内高端餐厅

来源: GU Bistronomy
Fine-dining餐厅、体验式咖啡馆、葡萄酒吧以及日式/韩式烤肉场所等高端餐饮与目的地型业态,在还剑、Tay Ho、Ba Dinh、Ciputra、Starlake,以及 Vincom Metropolis、Lotte Center 和 Aeon Mall Long Bien 等甲级购物中心仍然表现强劲。这些区域聚集了大量高收入居民、游客和企业高管。Savills《2024年第四季度零售洞察》显示,河内高端购物中心的出租率达到93%以上,其中餐饮是需求最高的租户类别之一[9]. 根据越南餐饮协会(2023年)的数据,高端餐厅收入的75-90%仍来自堂食,这意味着实体定位仍是核心价值驱动因素。.
However, the future is shifting beyond historic districts. New luxury townships such as Vinhomes Ocean Park (Gia Lam), The Manor Central Park (Hoang Mai – Thanh Tri), Ciputra, and Starlake are developing into high-income hubs supported by international schools, premium condos, and commercial streets. These areas are capturing younger, wealthy households and expat communities moving away from congested city centers. For premium brands, entering these districts early offers a first-mover advantage and lower rental risk before pricing escalates.
Mid-Casual, Fast-Casual, and Lifestyle Café Chains
Mid-casual restaurant in Hanoi
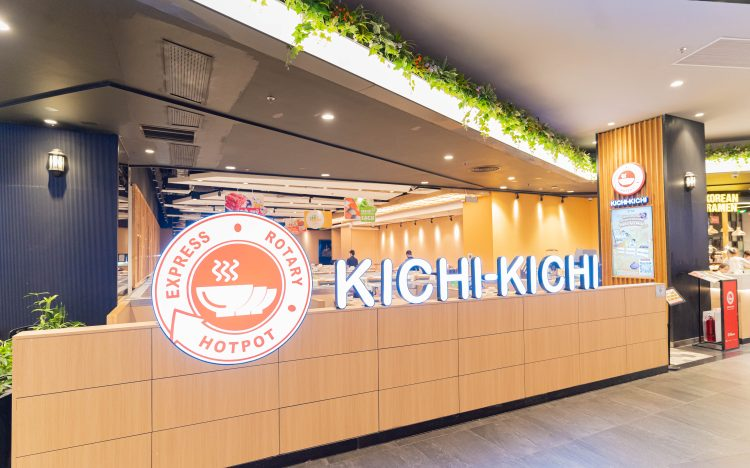
Source: Aeon Mall Ha Dong
Fast-casual restaurants and lifestyle café chains, including milk-tea, pizza/burger brands, Korean hotpot, and most coffee franchises, have historically concentrated in Cau Giay, Ha Dong, Thanh Xuan, and Hai Ba Trung. These districts provide dense daily foot traffic from students and office employees. iPOS.vn and Nestlé show that 30% of Hanoians aged 18-30 dine out or purchase café drinks 3-4 times per week[10]. Rents in these districts remain 20-40% lower than prime Hoàn Kiếm locations, creating a more sustainable cost structure for chains that depend on high visit frequency rather than luxury pricing.
Future growth for this segment is strongest in fast-urbanizing corridors instead of traditional commercial streets. First, the Hòa Lạc High-Tech Park axis, where new universities, R&D hubs, and tech employers are clustering, is expected to bring tens of thousands of young consumers. Second, Long Biên – Gia Lâm, fueled by Vinhomes Ocean Park, Aeon Mall Long Biên, and smart-city projects, is becoming a lifestyle-driven residential hub. As hybrid work reduces commuting, consumption will shift toward local neighborhood cafés and quick-service dining near homes. By 2022-2028, these “lifestyle neighborhoods” may rival Cầu Giấy and Thanh Xuân in consumer spending.
Value-segment, High-volume, and Delivery-first formats
以面馆、米饭和炸鸡连锁店、饮料亭和云厨房等为主的平价、高销量、外卖优先的餐饮模式正在经历最大规模的地域迁移。这些模式不再需要临街的显眼店面,而是依赖于低廉的租金、密集的人口密度和便利的物流。黄梅、北慈廉、东英和清池等地区的租金比市中心便宜40-601万越南盾,同时公寓数量也在快速增长。据Statista统计,越南在线食品配送市场在2023年达到13亿美元,预计到2027年将达到20亿美元。由于高层住宅区和年轻家庭的聚集,GrabFood和ShopeeFood在河内郊区的订单增长速度最快。
The most strategically important corridor for delivery-led operations over the next decade is the Nội Bài – Nhật Tân Bridge – Đông Anh development belt. Under Hanoi’s 2030 expansion plan, Đông Anh is expected to transition into a major new urban center. Early F&B entrants will gain access to a large delivery radius serving new residential areas, airport workers, and industrial parks.
Moreover, the rapid income growth in near-suburban districts like Hoai Duc, Gia Lam, Dong Anh, and Quoc Oai, where monthly income now reaches 20-23 million VND compared with only 11-15 million VND in 2020, witnessing the fastest income growth (+60-80%), suggests rising demand for mid-priced F&B concepts. These areas are increasingly populated by young families living in new apartment clusters, making them attractive for cafés, bakeries, and delivery-oriented formats with moderate rental costs.
结论
Across all segments, the definition of an optimal F&B location is changing. The future belongs to engineered consumer ecosystems: mega-townships, university corridors, tech parks, and delivery-optimized suburbs rather than heritage commercial streets. The brands that succeed will be those that map where population, disposable income, and delivery patterns are accelerating, not where they used to be. In this context, leading operators are already analyzing infrastructure pipelines, housing forecasts, and retail development plans instead of relying solely on foot-traffic observations.
* 如果您希望引用本文中的任何信息,请同时注明来源并附上原文链接,以尊重版权。.
| B&Company
自2008年以来,第一家专注于越南市场研究的日本公司。我们提供广泛的服务,包括行业报告、行业访谈、消费者调查、商业匹配。此外,我们最近开发了一个包含超过900,000家越南公司的数据库,可用于寻找合作伙伴和分析市场。. 如果您有任何疑问,请随时与我们联系。. info@b-company.jp + (84) 28 3910 3913 |
[1] Singh, S. (2025, September 12). Foreign food chains thrive in Vietnam’s growing F&B market. Vietnam Briefing. Retrieved from https://www.vietnam-briefing.com/news/foreign-food-chains-thrive-in-vietnams-growing-fb-market.html/
[2] VietNamNet. (2025, March 21). Vietnam’s F&B market focuses on sustainable growth. VietNamNet Global. Retrieved from https://vietnamnet.vn/en/vietnam-s-f-b-market-focuses-on-sustainable-growth-2382873.html (vietnamnet.vn)
[3] iPOS.vn & Nestlé Professional. (2025, October 12). Thông cáo báo chí:iPOS.vn và Nestlé Professional công bố Báo cáo Thị trường Kinh doanh Ẩm thực tại Việt Nam 6 tháng đầu năm 2025. Retrieved from https://ipos.vn/thong-cao-bao-chi-ipos-vn-va-nestle-professional-cong-bo-bao-cao-thi-truong-kinh-doanh-am-thuc-tai-viet-nam-6-thang-dau-nam-2025/
[4] B&Company. (2025, November 4). The trend of mass closure of F&B stores in the first half of 2025. https://b-company.jp/the-trend-of-mass-closure-of-fb-stores-in-the-first-half-of-2025/ (b-company.jp)
[5] CBRE Vietnam. (2024, January 24). Vietnam market outlook 2024. Retrieved from https://www.cbrevietnam.com/insights/books/vietnam-market-outlook-2024
[6] CBRE Vietnam. (2024, October 29). Hanoi figures Q3 2024. Retrieved from https://www.cbrevietnam.com/insights/figures/hanoi-figures-q3-2024 (cbrevietnam.com)
[7] iPOS.vn. (2025, May 16). Bức tranh toàn cảnh & xu hướng kinh doanh F&B năm 2025 – 2026:Doanh nghiệp bị“vỡ mộng”hay khai phá hướng đi riêng? iPOS.vn. https://ipos.vn/buc-tranh-toan-canh-xu-huong-fb-2025-2026/ (ipos.vn)
[8] Savills Vietnam. (2025). Hà Nội market report Q1 2025 [PDF]. Retrieved from https://www.savills.com.vn/pdf-folder/hanoi-mrq12025-en-1.pdf
[9] Savills Vietnam. (2024, April 2). Retail real estate market in Viet Nam: Q4/2024 performance and 2025 outlook. Retrieved from https://www.savills.com.vn/blog/article/220402/vietnam-eng/retail-real-estate-market-in-viet-nam–q4-2024-performance-and-2025-outlook.aspx savills.com.vn
[10] VietNamNet Global. (2024, April 13). More Vietnamese going out to eat despite economic difficulties. VietNamNet Global. https://vietnamnet.vn/en/more-vietnamese-going-out-to-eat-despite-economic-difficulties-2269252.html
相关文章







登录 / 注册
订阅新闻通讯