

 한국어
 English
 日本語
 Tiếng Việt
 简体中文
유가 충격은 동남아시아에서 이미 진행 중이던 청정에너지의 필요성을 더욱 가속화시켰습니다. 하지만 지역별 준비 상태는 극명한 차이를 보입니다.
294월2026
최신 뉴스 및 보고서 / 베트남 브리핑
댓글: 댓글 없음.

2026년 초 몇 달은 동남아시아 지역에 대한 스트레스 테스트 역할을 했습니다. 중동 지역의 긴장이 급격히 고조되어 호르무즈 해협이 폐쇄되면서 이 지역 액화천연가스(LNG)와 원유 수입량의 약 80%가 차질을 빚었습니다.1 이 “오일 쇼크”는 단순히 연료 가격을 끌어올린 데 그치지 않고, 글로벌 화석연료 시장에 종속된 경제의 구조적 취약성을 드러냈다.3
위기는 역내 현상이지만 대응은 점점 더 분절되고 있다. 회원국별 전환 경로에는 상당한 차이가 있다. 일부 국가는 보호주의적 보조금을 더욱 확대하는 반면, 다른 국가들은 특히 Vietnam의 녹색 전환을 통해 국가 경제 생존을 위한 수단으로 국내 생산 재생에너지로의 전환을 가속화하고 있다.
유가 변동성에 대한 노출: 수입국 vs. 수출국
이번 충격은 동남아시아를 순석유수지라는 단층선을 따라 양분한다. 수입국인 Philippines, Thailand, Vietnam, Singapore, 은 에너지 비용이 물류 및 공급망 전반으로 파급되면서 즉각적인 스태그플레이션 압력에 직면하고 있다. Philippines(걸프 지역 의존도 90%)는 2026년 3월 국가 에너지 비상사태를 선포했으며, Thailand는 경유 가격을 상한제로 묶었다. Singapore는 200일 이상의 전략 비축량을 보유하고 있음에도 2026년 인플레이션 전망을 상향 조정했다[1].
수출국인 Indonesia와 Malaysia 은 세입 증가를 경험했지만, 그 효과는 빠르게 약화되고 있다. Indonesia는 전체 US$22.5 billion 규모의 연료 보조금 예산을 US$70/barrel로 설정했으나, 전 세계 유가의 주요 기준으로 사용되는 Brent가 US$104 수준에 근접하면서 재정 격차가 확대되고 루피아에 부담을 주고 있다.[2], Malaysia는 최근의 재정 개혁에 힘입어 BUDI95 보조금을 유지할 수 있어 상대적으로 완충력이 높지만, 국내 정제를 위해 중질 원유를 재수입하고 기준유 가격 변동에 여전히 노출되어 있어 영향에서 자유롭지 않다.
표 1: 국가별 오일 쇼크 취약성 — 동남아시아
*주: PH: Philippines, VN: Vietnam, TH: Thailand, SG: Singapore, ID: Indonesia, MY: Malaysia
| 지표 | 순수입국 — PH, VN, TH, SG | 순수출국 — ID, MY |
| 교역 구조 | 수입 원유 및/또는 정제 제품에 의존 | 순탄화수소 수출국이며, 국내 보조금 의무가 일부 상쇄 요인으로 작용 |
| 중동산 원유 의존도[3] | • VN: 약 85%
• SG: 약 77% • TH: 약 70% • PH: ~52% |
• ID: 걸프 지역에서 원유의 약 35%를 조달(보조금으로 인해 보조금 비용은 여전히 증가)
• MY: 약 25% (국내 공급량과 혼합하기 위해 멕시코만산 중질유를 재수입) |
| 전략 비축량[4] | • SG: 200일 이상
• TH & PH: 40~60일 • VN: 약 65일 |
• MY: 약 60일
• ID: 약 20~30일 |
| 주요 리스크 | 비용 상승발 인플레이션 및 통화 압력:
• IMF는 동남아시아의 인플레이션이 2026년에 2.6%까지 상승할 것으로 전망한다.[5]; • Brent 가격이 배럴당 US$15 상승할 때마다 PH의 경상수지 적자는 GDP의 약 0.7%만큼 확대[6] |
보조금 의무에 따른 재정적자 확대:
• ID는 보조금 예산을 배럴당 US$70로 설정했으나, 현재 Brent는 배럴당 약 US$1042 |
| 에너지 믹스 취약성 | LNG/Brent 현물 가격에 대한 높은 민감도:
• VN의 Nghi Son은 쿠웨이트산 원유 공급 원료에 연동[7]; • TH는 발전용 걸프산 가스에 의존[8] |
• ID: 석탄과 국내산 팜유에 대한 의존도가 높음;
• MY: 혼합 원유 모델(경질 스위트 원유 수출 및 중질 원유 수입)은 취약성을 줄여주지만, 보조금 비용에는 여전히 영향을 미칩니다. |
| 충격 전이 | 소매가격 인상 및 물류 할증료[9]:
• PH: 국가 에너지 비상사태; • VN: 국내선 운항 취소; • TH: 주요 석유화학 플랜트 가동 중단 |
국가 신용도 및 통화 압력:
• ID의 통화 약세; USD 대비 실질금리 차 축소; 6 • MY의 신용 전망은 다변화된 수익 구조 덕분에 안정적(에너지 가격 상승 시 가스 수출로 수혜) |
| 정책 대응[10] | • VN: 0% 석유 관세 (2026년 4월~6월)[11] ; 재택근무 장려
• PH: 소비세 인하, 필리핀 국영 석유회사(PNOC) 긴급 수입, 주 4일 근무제 • TH: 경유 가격 상한제, 재택근무 의무화 • SG: 싱가포르 통화청(MAS)의 통화 긴축 정책 시행, 재정 준비금 투입 |
• ID: 연료 보조금 유지; 원격근무 도입
• MY: BUDI95 보조금 유지; 2026년 중반까지 "충분한 재정 여력" 확보 |
B&Company의 합성
주목할 사례 연구: 회복탄력성을 위한 다양한 경로
Indonesia: 보조금 개혁과 바이오연료 확대
인도네시아는 역사적으로 가격 상한제를 통해 국민을 보호해 왔지만, 2026년 위기로 인해 재정 적자가 GDP의 3.5%라는 법정 한도에 근접하게 되었습니다.[12] To mitigate this, Jakarta has revived its ambitious biofuel mandate. In March 2026, President Prabowo Subianto announced a transition to a 50% biodiesel blend (B50) by the second half of 2026, accelerating the previous B40 timeline to reduce the gasoil import bill.
Vietnam: Rapid demand growth and renewable ambitions
The Vietnam green transition is driven by a unique dual mandate: sustaining 10% annual GDP growth while meeting net-zero commitments. Under the revised Power Development Plan VIII (PDP8), Vietnam aims to increase its renewable capacity to nearly 50% of the energy mix by 2030.[13] A significant shift is the rise of domestic corporations like Vingroup (via VinEnergo), which is spearheading a US$4.5 billion offshore wind project to replace aging coal assets.[14]
The first offshore wind data transfer collaboration in Vietnam is between VinEnergo (Vingroup) and the FIMO Center
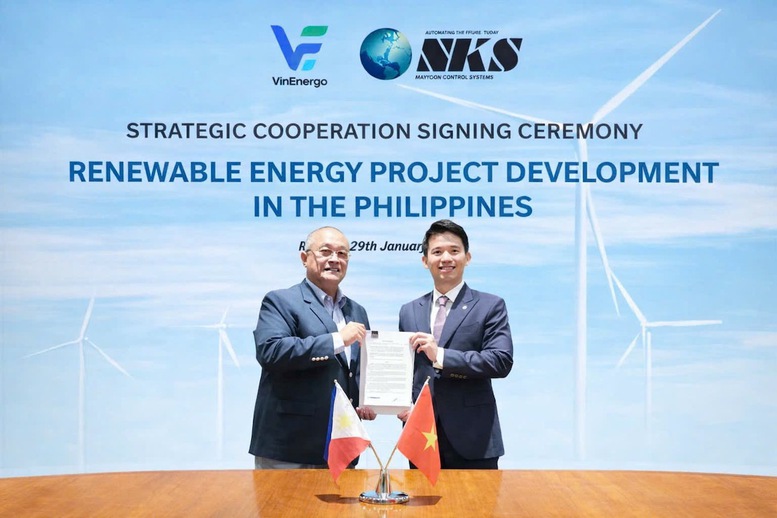
출처: VinGroup
Thailand: The EV hub strategy
태국은 이번 위기를 발판 삼아 전기차 분야에서 '동양의 디트로이트'로서의 입지를 공고히 했습니다. 2026년 1월까지 신차 판매량 대비 전기차 보급률은 사상 최고치인 48%를 기록할 것으로 예상되며, 이는 차량당 최대 10만 바트(약 2,700달러)의 보조금 지급과 8%에서 2%로 인하된 전기차 3.5 인센티브 제도의 지원에 힘입은 결과입니다.[15] This strategy aims not only to reduce fuel consumption but to transition the domestic automotive workforce into a new high-tech manufacturing sector.
Philippines: Energy security challenges
The Philippines remains one of the most price-sensitive markets. In March 2026, President Marcos Jr. signed Republic Act No. 12316, granting emergency powers to suspend fuel excise taxes once global oil prices hit US$80 per barrel.[16] Unlike Thailand or Vietnam, the Philippines’ transition is hampered by infrastructure gaps, leading to a heavy reliance on emergency subsidies for transport workers.
Policy comparison: Fiscal sustainability vs. Reform
The 2026 crisis has highlighted a divergence in regulatory philosophy. “Market-driven” economies (Vietnam, Philippines) allow prices to reflect global trends but deploy temporary tax holidays, whereas “subsidized” economies (Indonesia, Malaysia) prioritize social stability at the cost of fiscal health.
| Policy category | Implementation example (2026) | Effectiveness / Risk |
| Tax interventions | Vietnam/Philippines: 0% environmental/excise tax | High flexibility; protects business margins but hurts revenue |
| Price caps | Indonesia/Thailand: Diesel capped at specific price | High social stability; risk of hoarding & massive state debt |
| Demand side | Philippines: 4-day workweek in public sector | Low cost; effectively signals conservation but limits productivity |
| Fuel switching | Vietnam: Nationwide E10 rollout by June 1, 2026 | Structural resilience; requires consumer trust & engine compatibility |
B&Company의 합성
Green transition readiness index 2026
The oil shock has not created Southeast Asia’s clean energy imperative — it has accelerated one already underway. But readiness varies sharply across the region.
Singapore and Malaysia lead on green finance architecture: Singapore has established a carbon tax and trading framework, while Malaysia pioneered sustainability-linked bonds and ASEAN Green Bond Standards.[17] Vietnam is the region’s standout deployment story, with the total renewable energy sources (wind, solar, biomass) accounting for approximately 24,453 MW at the end of 2025.[18] The crisis is now compounding that momentum: the introduction of direct power purchase agreements is allowing large companies like LEGO and Samsung to buy electricity directly from wind and solar producers, potentially doubling the renewable share in Vietnam’s power mix. Vietnam ranked 2nd among the top developing economies attracting the most FDI in renewable energy between 2015 and 2022, at approximately 106.8 billion USD.[19]
The Philippines is following, having fully opened its solar, wind, biomass, and tidal sectors to foreign ownership and approved over 100 key energy projects, including offshore wind, hydropower, and infrastructure expansions.[20] Indonesia, however, remains constrained. Its energy transition is limited by a state-dominated electricity market, fragmented governance, and weak grid readiness, and protectionist rules continue to cap foreign ownership in renewables.[21] The gap between Vietnam and Indonesia on transition readiness is arguably the region’s most consequential divergence heading into the decade.
Across all markets, the financing shortfall is structural. The International Energy Agency (IEA) estimates annual clean energy investment in Southeast Asia must rise fivefold to US$190 billion by 2035, for the region to achieve its goals.[22]
Regional trends and integration: moving toward unity
The shock has injected fresh urgency into the long-stalled ASEAN Power Grid (APG). 2026 marks the start of the ASEAN Plan of Action or Energy Cooperation 2026–2030 (APAEC) implementation cycle, signaling the APG moving from strategic planning toward coordinated infrastructure development. The Philippines, as the 2026 ASEAN Chair, has prioritized APG integration and initiated grid interconnection talks with Malaysia. Yet the hard constraints remain.
“Vision vs. voltage” remains a challenge. As of late 2024, the region has only 7.7 GW of interconnection capacity across 9 priority projects.[23] Progress is being catalyzed by the ASEAN Power Grid Financing Facility (APGF), which aims to harmonize technical standards and dispute resolution by the 2027 Singapore chairmanship.
Implications for investors: high-potential markets
For investors, the 2026 shock is functioning as a stress test and a signal simultaneously. Three themes stand out.
1. Vietnam, Indonesia, and the Philippines offer the most potential in the short term to access the clean energy sector
Solar project profitability in the 3 countries can rise up to 9 percentage points, driven by battery integration that makes dispatchable solar economically feasible,[24] and both markets now have Direct Power Purchase Agreement (DPPA) frameworks to monetize it. Vietnam, the Philippines, and Indonesia together attracted US$4.6 billion in clean energy investment in 2024, with Brookfield Asset Management committing capital across all three.[25]
2. Indonesia and the Philippines’ critical minerals represent a longer-horizon opportunity
Indonesia and the Philippines have the potential to anchor the global supply chain for critical minerals driving the energy transition, but currently lack domestic processing capabilities,[26] creating a clear greenfield investment thesis for battery supply chain investors.
3. Grid infrastructure is the region’s most undersupplied asset class
The finalization of the APAEC 2026–2030 and renewal of the APG enhanced MOU mark a crucial opportunity to transform long-standing commitments into meaningful regional energy integration, and the first movers in cross-border transmission financing will define the region’s energy architecture for decades.
The transition from oil dependence to grid-scale renewables will not be linear. But the 2026 shock has compressed the timeline, and for investors with the patience and local knowledge to navigate regulatory heterogeneity, Southeast Asia’s energy reordering represents one of the decade’s most consequential allocation opportunities.
결론
The 2026 oil shock has proven that there is no one-size-fits-all transition. Indonesia is betting on palm-based energy independence, Thailand on becoming an EV manufacturing hub, and Vietnam’s green transition on a massive, grid-scale renewable overhaul supported by international finance.
Despite these different pathways, a shared momentum has emerged. Energy security is no longer viewed as a matter of securing supply, but as a structural shift toward domestic, low-carbon generation. As global standards like the EU’s Carbon Border Adjustment Mechanism (CBAM) take effect, the “greenness” of a nation’s energy grid will become the ultimate determinant of its industrial competitiveness in the post-oil-crisis era.
더 보기
* 이 기사에서 정보를 인용하고자 하신다면 출처를 원문 기사 링크와 함께 인용하여 저작권을 존중해 주시기 바랍니다.
| B&Company
2008년부터 베트남에서 시장 조사 전문 기업으로 활동해 온 최초의 일본 기업입니다. 산업 보고서, 업계 관계자 인터뷰, 소비자 설문 조사, 비즈니스 매칭 등 폭넓은 서비스를 제공합니다. 또한, 최근에는 베트남 기업 90만 개 이상의 데이터베이스를 구축하여 파트너 발굴 및 시장 분석에 활용하고 있습니다. 문의 사항이 있으시면 언제든지 저희에게 문의해 주세요. info@b-company.jp + (84) 28 3910 3913 |
[1] https://carnegieendowment.org/posts/2026/04/southeast-asias-agency-amid-the-new-oil-crisis
[2] https://jakartaglobe.id/business/indonesia-says-no-energy-crisis-as-philippines-declares-one
[3] https://carnegieendowment.org/posts/2026/04/southeast-asias-agency-amid-the-new-oil-crisis
[4] https://www.thesoutheastasiadesk.com/p/southeast-asia-scrambles-as-strait
[5] https://www.imf.org/en/blogs/articles/2026/04/16/asias-economic-resilience-is-being-tested-by-the-energy-shock
[6] https://think.ing.com/articles/oil-shock-for-asia-identifying-the-first-pressure-points/
[7] https://blog.investvietnam.co/104-gasoline-industry-in-vietnam-statistics-data-trends-in-2026/
[8] https://energytracker.asia/thailand-energy-sector/
[9] https://www.npr.org/2026/03/26/nx-s1-5760763/southeast-asia-is-being-hit-hard-by-irans-cutoff-of-oil-and-gas
[10] https://caseforsea.org/energy-security-in-the-shadow-of-war-how-case-countries-are-navigating-the-2026-fuel-crisis/
[11] https://b-company.jp/vietnam-fuel-price-update-weekly-rising-volatility-and-implications-for-business/
[12] https://www.mk.co.kr/en/world/12009974
[13] https://www.vilaf.com.vn/blog/vietnams-revised-pdp-8-a-strategic-path-for-national-electricity-development/
[14] https://b-company.jp/vietnams-renewable-energy-boom-southeast-asias-leader-with-vingroup-emerging-as-a-key-domestic-player/
[15] https://source.benchmarkminerals.com/article/thailand-s-ev-sales-surge-to-record-levels-in-january-2026
[16] https://pco.gov.ph/news_releases/pbbm-signs-ra-12316-granting-the-president-emergency-powers-to-suspend-reduce-fuel-excise-tax/
[17] https://thefulleracademy.com/practices-of-financial-institutions-towards-green-financing-in-asean-region/
[18] https://en.evn.com.vn/d/en-US/news/Vietnams-power-system-ranks-second-in-ASEAN-60-163-501175
[19] https://en.nhandan.vn/fdi-attraction-to-prioritise-green-projects-post145700.html
[20] https://www.thestar.com.my/business/business-news/2026/04/09/budi95-is-seen-as-a-right-step-in-targeted-fuel-subsidy-reform-for-malaysia-says-world-bank
[21] https://ieefa.org/resources/building-credibility-indonesias-energy-transition-insights-etm-and-jetp-indonesia
[22] https://www.reuters.com/sustainability/southeast-asia-needs-boost-investments-five-fold-by-2035-meet-climate-goals-iea-2024-10-21/
[23] https://asean.org/adb-and-world-bank-group-launch-the-asean-power-grid-financing-initiative-with-the-asean-secretariat-and-the-asean-centre-for-energy-ace/
[24] https://ember-energy.org/latest-updates/adding-storage-can-boost-solar-projects-profitability-in-indonesia-viet-nam-and-the-philippines/
[25] https://ember-energy.org/latest-insights/from-emission-intensive-to-investment-hotspots-championing-renewables-in-3-asean-economies/country-snapshots-and-opportunities/
[26] https://peacehumanity.org/monitor/false-promises-of-battery-minerals-mining-inindonesia-and-the-philippines/
관련기사





로그인 / 회원가입
뉴스레터 구독