

 한국어
 English
 日本語
 Tiếng Việt
 简体中文
제70호 시행령에 따라 베트남에서 개인용 QR 코드 사용이 감소할 것으로 예상되며, 이에 따라 가내 사업체들은 전문 서비스로 전환해야 할 필요성이 대두될 것입니다.
141월2026
최신 뉴스 및 보고서 / 베트남 브리핑
댓글: 댓글 없음.

Thanks to its convenience and accessibility, payments using QR codes have been rapidly adopted in Vietnam’s retail landscape, including household businesses and micro-merchants. However, the introduction of Decree 70 and the shift from lump-sum taxation to revenue-based declaration expose structural weaknesses in the widespread use of personal QR codes. Under this regulatory pressure, the use of personal QR codes will inevitably decline, urging household businesses to switch to specialized services.
The popularity of QR Code
Vietnam has experienced rapid growth in cashless transactions over the past decade, with QR code payments emerging as one of the most widely adopted payment methods. According to the State Bank of Vietnam, in the first nine months of 2025, cashless transaction increases 43.3% in volume and 24.2% in transaction value compared to the same period the previous year. Particularly, transactions using QR Code have impressive growth: 61.6% in volume and 150.7% in transaction value[1].
QR codes are particularly popular among household businesses and street vendors because they are inexpensive, easy to deploy, and do not require POS terminals, which significantly lowers adoption barriers for micro-merchants[2]. Any shop-owner can adopt the method quickly by opening a bank account, generating a personal QR code, and placing it at the counter. As a result, QR payments have become embedded in daily consumer behavior, including informal retail environments such as wet markets and roadside stalls[3].
QR 코드가 있는 녹색 찹쌀밥 판매대
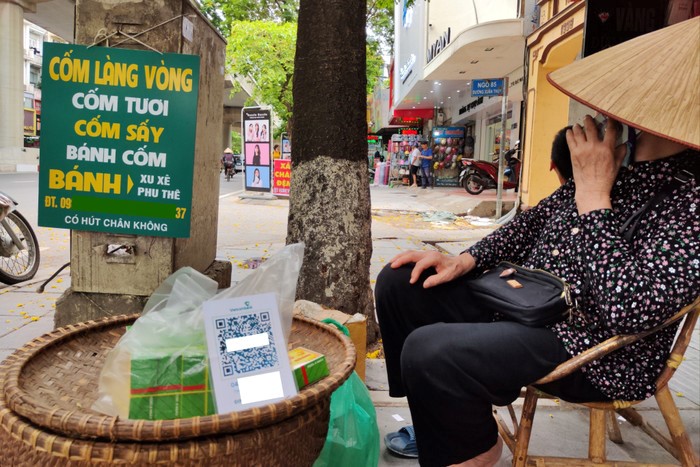
출처: Dan Viet
New tax regulation for household businesses
Vietnam’s regulatory landscape for household businesses is undergoing a fundamental shift that directly affects how QR codes can be used. Under the new tax framework introduced through Decree 70, the government is transitioning household businesses away from the lump-sum tax system toward a self-declaration regime based on actual revenue. Household businesses will be required to maintain proper accounting records, declare revenue periodically, and issue electronic invoices connected to tax authorities’ systems[4]. This represents a major departure from the previous model, where household businesses paid a fixed estimated tax and were not required to systematically document each transaction.
Problems of using Personal QR Code
Within this new regulatory context, the widespread use of personal QR Codes for business transactions has emerged as a problem.
Regulatory and Compliance Risks
When the new tax regime is issued, the QR Code for transfer and payment is also differentiated. Despite both relying on QR codes as a scanning interface, QR transfer is a peer-to-peer bank transfer method in which the QR code contains personal account information, allowing money to be sent directly to an individual’s bank account. This is the Personal QR Code method that business households have widely adopted. In contrast, QR payment is a payment solution issued to a registered business account. QR Pay transactions are recognized as commercial payments, are recorded as sales revenue, and can be automatically linked to POS systems, e-invoicing platforms, and tax authority reporting requirements[5].
Using Personal QR codes makes it difficult to distinguish between personal and business income. Under the new tax regime, this creates significant compliance risks, as tax authorities require transparent, auditable transaction records that align with declared revenue and issued e-invoices. The continued use of personal QR codes may expose household businesses to legal risks during tax inspections, including difficulties in explaining transaction flows and potential suspicions of under-reporting revenue[6]. In some cases, this can raise suspicions of tax evasion or unclear revenue reporting.
Lack of consumer protection
Another major drawback of using personal QR codes for business transactions is the limited protection of consumer rights. Payments made via personal QR codes are legally classified as peer-to-peer bank transfers rather than commercial transactions, meaning they fall outside the scope of formal merchant payment regulations. As a result, consumers often do not receive official receipts or invoices, and there is no standardized mechanism for refunds, chargebacks, or dispute resolution when goods are defective, services are not delivered, or fraud occurs. In cases of mistaken transfers or scams involving personal QR codes, banks are generally unable to reverse transactions without the recipient’s consent, leaving consumers exposed to financial loss[7].
Incompatibility with international payment systems
Another limitation of personal QR codes is their inability to connect with international payment networks. Personal QR transfers are typically tied to domestic bank accounts and local payment rails, such as interbank transfer systems within Vietnam, and are not designed to support foreign cards, international wallets, or global settlement standards. The lack of international compatibility not only limits revenue opportunities for household businesses but also creates friction in key sectors such as tourism and services, where foreign customer spending is significant[8]. As Vietnam promotes digital payments as part of its economic modernization strategy, this gap further strengthens the case for transitioning household businesses away from personal QR transfers
Services from major banks to support business households
Amid the regulatory pressure, household businesses face significant challenges when transitioning to registered payment solutions linked to business accounts. Common concerns include transaction fees, which are perceived as reducing already-thin margins; installation or setup costs for POS systems or software; and operational complexity, such as learning new apps, managing digital invoices, and reconciling transactions for tax declaration. Recognizing these barriers, Vietnamese banks have begun positioning themselves not merely as payment service providers but as digital transformation partners for household businesses.
MB 은행 – 디지털 솔루션 MB 판매자
Through its MB Seller solution, MB offers an integrated digital ecosystem that allows household businesses to accept QR payments, manage transactions, and issue electronic invoices using only a smartphone, without requiring POS devices or additional hardware. This significantly reduces installation and upfront costs, one of the biggest barriers for micro-merchants. Importantly, the mobile phone app – mSeller is designed with tax compliance in mind, enabling transaction records to align with revenue declaration and electronic invoicing requirements under the new tax regime[9]. Using the app, household businesses can issue e-invoices using a smartphone[10].
Vietcombank – 가맹점 결제 플랫폼 DigiShop
Vietcombank supports household businesses through VCB DigiShop, a merchant-oriented digital platform that emphasizes standardization, transparency, and regulatory alignment. DigiShop enables registered merchant QR payments and integrates transaction records with business account management, helping household businesses clearly separate personal and business cash flows. Importantly, Vietcombank’s solution is designed to connect with Vietnam’s broader digital commerce and tax ecosystem, including compatibility with eTax platforms and third-party POS and store management software such as KiotViet[11].
Agribank – Support Package for Household Businesses
Through its service package, Agribank addresses one of the most pressing barriers to adopting registered payment solutions: installation and service costs. Under this program, Agribank offers free installation and usage of digital payment and POS-related services for household businesses for up to three years (through 2028), significantly lowering the financial burden associated with transitioning to compliant merchant payment systems[12]. Besides, Agribank also leverages its extensive branch network and customer base, particularly in rural and semi-urban areas to provide hands-on guidance and digital banking access for household businesses[13].
Other banks such as Techcombank, BIDV and Vietinbank also accelerate their support to help household businesses adopt in compliance with Decree 70 with discounted service packages and other innovative solutions. One prominent solution is SoftPOS, which allows merchants to accept card and wallet payments directly on NFC-enabled smartphones without installing traditional POS hardware[14]. This solution is cost-effective and suitable for the Vietnamese context, considering the widespread ownership of smartphones and Internet connections in Vietnam. According to the Ministry of Information and Communications, the smartphone ownership rate among adults is 84.4% in 2023 and is targeted to reach 100% in 2025[15]. The Internet adoption rate is increasing consistently over time.
Vietnam Internet adoption rate (2016-2025)
단위 : %
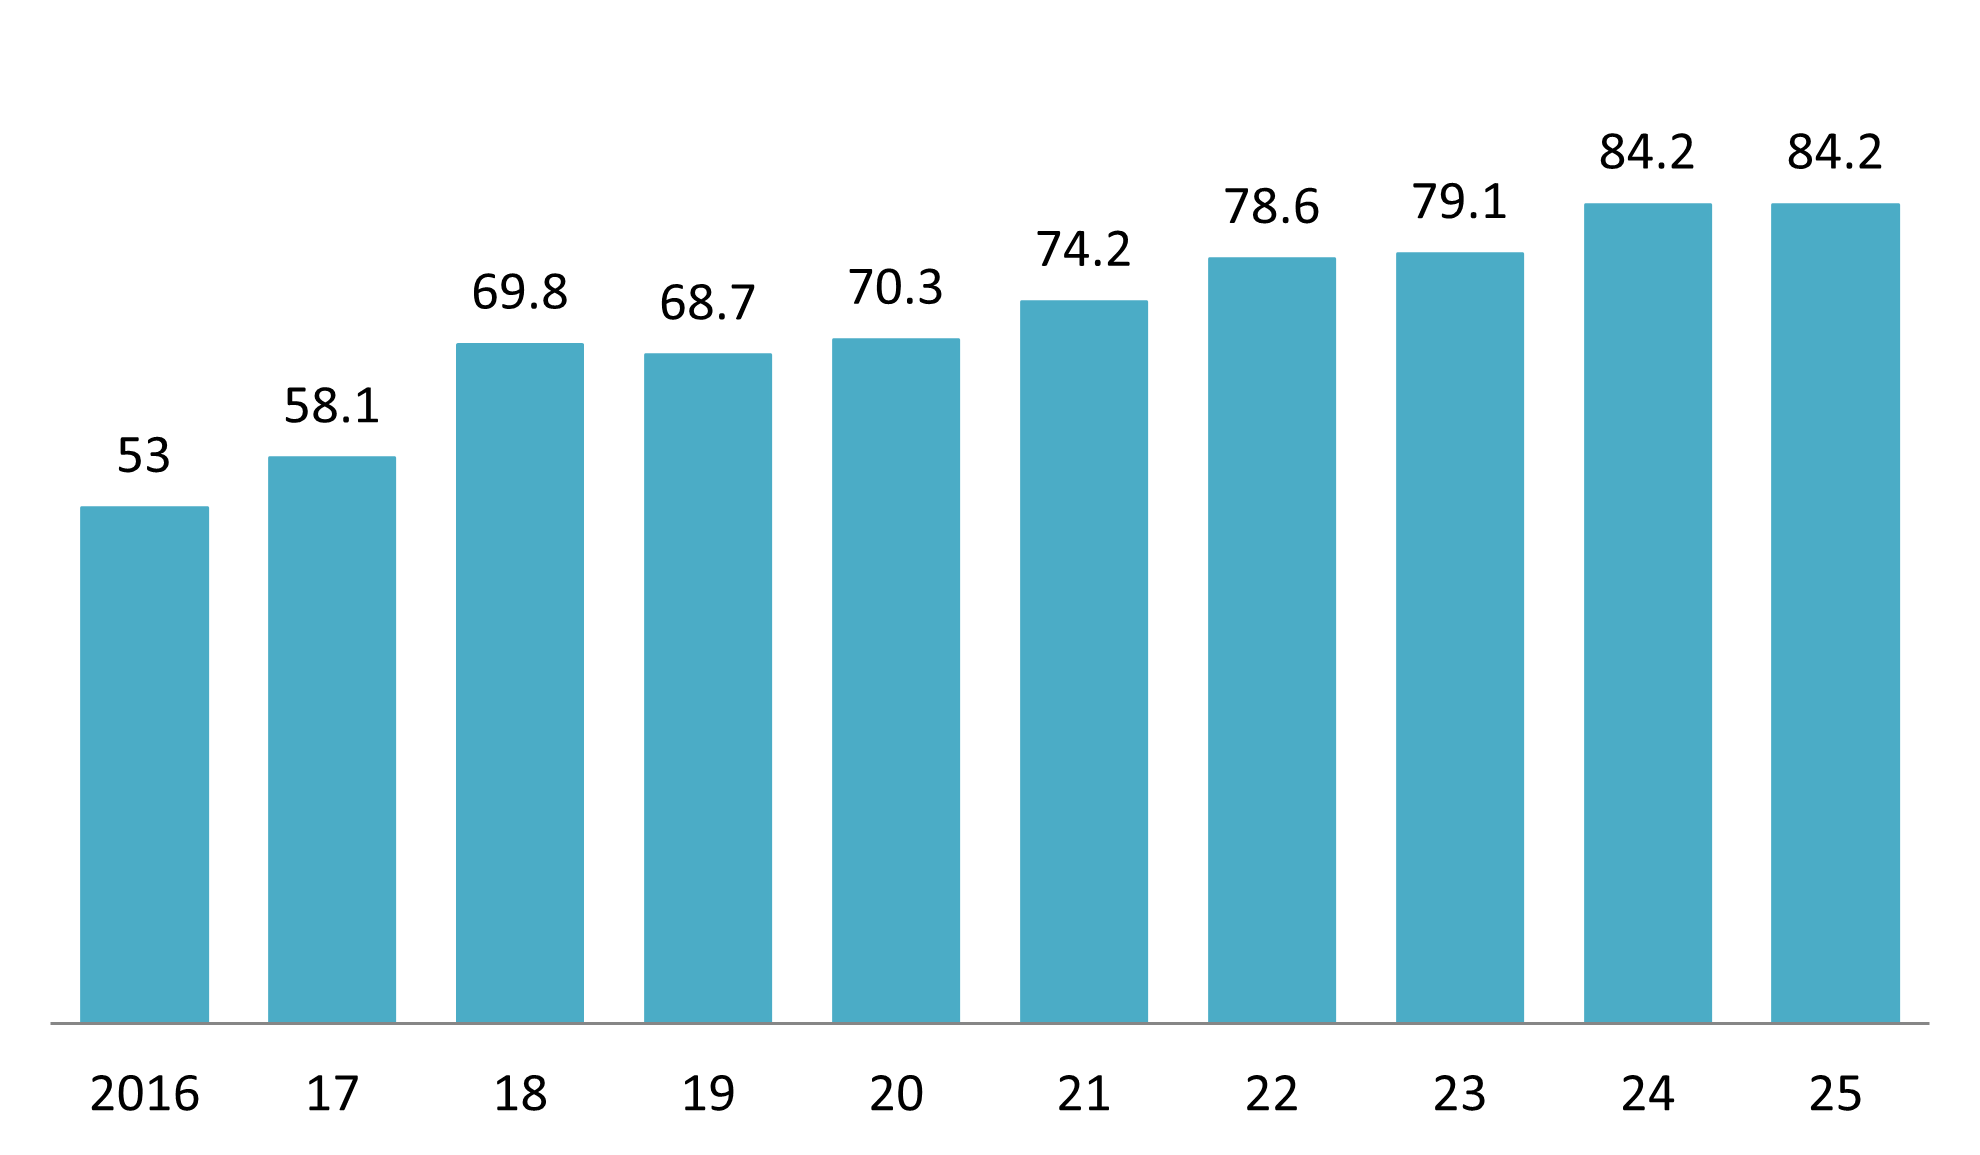
출처: DataReportal
결론
The decline of personal QR codes and the mandatory shift toward registered payment methods under Decree 70 fundamentally reshape Vietnam’s household business landscape. The formalization of household business transactions creates clearer revenue data, stronger compliance infrastructure, and more standardized payments, improving market transparency. This opens opportunities for foreign fintech firms, payment service providers, POS and accounting software vendors, and cross-border payment networks to partner with local banks, integrate into Vietnam’s evolving digital payment ecosystem, and serve a newly formalized merchant base. In the medium term, the decline of personal QR codes and the rise of specialized accounts are likely to strengthen Vietnam’s investment attractiveness by aligning its retail payment infrastructure more closely with international standards.
* 이 기사에서 정보를 인용하고자 하신다면 출처를 원문 기사 링크와 함께 인용하여 저작권을 존중해 주시기 바랍니다.
| B&Company
2008년부터 베트남에서 시장 조사 전문 기업으로 활동해 온 최초의 일본 기업입니다. 산업 보고서, 업계 관계자 인터뷰, 소비자 설문 조사, 비즈니스 매칭 등 폭넓은 서비스를 제공합니다. 또한, 최근에는 베트남 기업 90만 개 이상의 데이터베이스를 구축하여 파트너 발굴 및 시장 분석에 활용하고 있습니다. 문의 사항이 있으시면 언제든지 저희에게 문의해 주세요. info@b-company.jp + (84) 28 3910 3913 |
[1] Government News, QR payments are booming and require comprehensive standardization (https://baochinhphu.vn/thanh-toan-qr-bung-no-va-yeu-cau-chuan-hoa-toan-dien-10225111919305399.htm)
[2] VnEconomy, Opportunities for QR payment growth (https://en.vneconomy.vn/opportunities-for-qr-payment-growth.htm)
[3] Vietnam Education E-Magazine, Digital transformation involves changing habits towards cashless payments (https://giaoduc.net.vn/chuyen-doi-so-bang-thay-doi-thoi-quen-de-thanh-toan-khong-dung-tien-mat-post253763.gd)
[4] Official: businesses with revenue under 500 million VND will still be required to keep accounting records in 2026 (https://thuvienphapluat.vn/phap-luat/ho-tro-phap-luat/chinh-thuc-doanh-thu-duoi-500-trieu-ho-kinh-doanh-van-phai-lam-so-sach-ke-toan-nam-2026-chi-tiet-ra-177463-250119.html)
[5] VnEconomy, Shift towards merchant-based QR payments (https://en.vneconomy.vn/shift-towards-merchant-based-qr-payments.htm)
[6] VnEconomy, Who benefits when upgrading QR money transfers to QR payments? (https://vneconomy.vn/ai-huong-loi-khi-nang-hang-qr-chuyen-tien-len-qr-thanh-toan.htm)
[7] VnEconomy, Shift towards merchant-based QR payments (https://en.vneconomy.vn/shift-towards-merchant-based-qr-payments.htm)
[8] Business and Integration E-Magazine, QR Code payments are booming, but many businesses still use personal codes? (https://doanhnghiephoinhap.vn/thanh-toan-qr-code-bung-no-nhung-nhieu-ho-kinh-doanh-van-dung-ma-ca-nhan-121646.html)
[9] MB Bank, MB provides MB Seller digital solutions (https://www.mbbank.com.vn/chi-tiet/tin-mb/mb-cung-cap-bo-giai-phap-so-mb-seller-dong-hanh-cung-ho-kinh-doanh-but-toc-60-ngay-chuyen-doi-ke-khai-thue-2025-11-24-16-3-3/6828)
[10] Government News, MB offers the mSeller app: Businesses can issue electronic invoices with just a phone (https://baochinhphu.vn/mb-tang-ung-dung-mseller-ho-kinh-doanh-chi-can-dien-thoai-la-co-the-xuat-hoa-don-dien-tu-102250614201231134.htm)
[11] Vietcombank, VCB Digishop – A comprehensive solution to support household businesses. (https://www.vietcombank.com.vn/vi-VN/To-chuc/SMEs/Danh-sach-tin-noi-bat-KHSMEs/Articles/2025/06/25/VCB-DIGISHOP-dong-hanh-cung-ho-kinh-doanh)
[12] 아그리뱅크(Agribank)는 "아그리뱅크가 가계 사업에 함께합니다"라는 상품 및 서비스 패키지를 출시했습니다. (https://www.agribank.com.vn/vn/khuyen-mai/khuyen-mai-ca-nhan/khuyen-mai-ngan-hang-so/agribank-ra-mat-goi-san-pham-dich-vu-agribank-dong-hanh-cung-ho-kinh-doanh)
[13] Agribank, Agribank accelerates support for business households in digital transformation and implementation of Decree 70/2025/ND-CP (https://www.agribank.com.vn/vn/ve-agribank/tin-tuc-su-kien/tin-ve-agribank/hoat-dong-agribank/agribank-tang-toc-ho-tro-ho-kinh-chuyen-doi-so-va-thuc-thi-nghi-dinh-70-2025-nd-cp)
[14] 테크콤뱅크, 소프트POS – 편리하고 비용 효율적인 카드 결제 솔루션 (https://techcombank.com/thong-tin/blog/softpos)
[15] 결정 제36/QĐ-TTg호, 2021년~2030년 정보통신 인프라 계획 승인 (2050년까지의 비전 포함) (https://thuvienphapluat.vn/van-ban/Xay-dung-Do-thi/Quyet-dinh-36-QD-TTg-2024-phe-duyet-Quy-hoach-ha-tang-thong-tin-va-truyen-thong-2021-2030-595184.aspx)
관련기사




로그인 / 회원가입
뉴스레터 구독